Essential Income Fund
Fixed Returns with
Significant Downside Protection
Income fund designed for dependable cash flow, disciplined downside protection, and greater certainty
Invest $100,000+ and add 1% to your term's rate: up to 10.50% fixed
Performing senior lien portfolio · Verified accredited investors only · SDIRA eligible
8-10.5%$100K+ adds 1% to your term's rate
$20,000Minimum investment
MonthlyInterest distributions
24-60Month certificate terms
$0Management or performance fees
Investor Benefits
What the fund is designed to deliver
At Essential Investment Group, we built a private real estate debt fund focused on capital preservation, for investors who prefer contractual income over discretionary distributions, without owning property or managing tenants. The fund lends privately to real estate borrowers and buys performing senior lien notes at a discount. Your certificate pays a fixed contractual rate, secured by real property.
Inflation-Protected Inflation erodes idle cash and low-yield savings first. Your certificate's fixed rate is set well above typical bank yields, and the collateral behind it is real property, a hard asset rather than a paper promise.
Recession-Resistant In a downturn, equity investors wait to hear whether distributions will continue. Your income is contractual: borrowers owe the same payment in a soft market as in a strong one, and borrower equity absorbs a decline before the fund's position is touched.
Uncorrelated to Public Markets When stocks fall, everything correlated with them falls on the same day. Private, asset-backed loans do not trade on public exchanges and do not reprice with the daily mood of the markets. Your return comes from contractual interest, not from the direction of the S&P.
Secured by Real Assets Every certificate is backed by performing senior lien positions on real property with a real address, not a ticker or a token. Independent valuations and third-party due diligence confirm the collateral before a dollar moves, and a recorded legal claim stands behind your investment.
Passive Investment You should not need a second career to earn real estate income. We manage sourcing, underwriting, origination, servicing, and asset management; you receive monthly interest from day one. No tenants, no rehabs, no 2 a.m. phone calls.
How It Works
Three steps to monthly income
01
You invest Review the offering documents, then choose a certificate: 24, 36, or 60 months, starting at $20,000.
02
The fund lends Your capital goes into performing senior lien loans and notes, secured by real property and independently valued before a dollar moves.
03
You get paid Interest accrues from the day you fund and is paid to you monthly, with principal scheduled to return at maturity.
Model Returns Calculator
What would your income look like?
Investments of $100,000 or more add 1% to your term's rate, applied to the entire amount, for up to 10.50% fixed.
$
Certificate term
$475Projected monthly income
9.50%Applied fixed rate
$28,500Total interest over term
$88,500Distributions plus scheduled principal at maturity
Cumulative interest distributed
Hypothetical illustration based on term sheet rates, assuming interest is paid monthly and principal is scheduled to be returned at maturity. Not a guarantee of future distributions. See the Private Placement Memorandum for complete terms.
About Us
Why investors work with us
Real collateral, not speculation Every asset is secured by real property. Your investment is backed by our ability to source, underwrite, and manage mortgage note portfolios, not by projections or market sentiment.
Diversification By spreading your investment capital across multiple notes and loans simultaneously, we potentially reduce single-asset exposure. One investment, many senior lien positions.
Aligned interests We invest our own capital in every deal we manage, alongside yours. Your capital supports our shared pipeline, and we earn together.
Who this is for
Family Offices · Crypto & Alternative Asset Investors · Doctors & Medical Professionals · Experienced Real Estate Investors · Self-Directed IRA Investors · Attorneys & Legal Professionals · Non-Profit Organizations
Portfolio Details
Portfolio at a glance
A portfolio of performing senior liens, purchased at a discount and independently valued.
48%Weighted loan-to-value, vs about 75% national average
100%Senior lien position on every asset
$1MM+Collateral value behind the portfolio
Principal & Manager
Who manages your investment
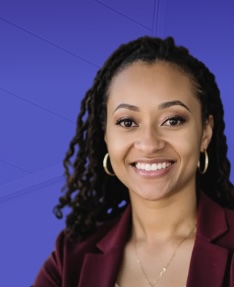
Sierra Davis
Principal & Fund Manager
Sierra brings more than 8 years of experience in mortgage note investing, leading the company's acquisitions, originations, and asset management. Sierra's background in analytics and AI informs a rigorous, data-driven approach to evaluating investment opportunities and managing risk. Her work also extends to educating over 700 investors on alternatives through a weekly newsletter and webinars. She holds an MBA in Data Science and a BS in Management Information Systems.
Due Diligence
The questions serious investors ask
Direct answers, in the order a careful investor would ask them. Ask these questions of every private lender, including us.
What is Essential Income Fund? +
Essential Income Fund, LLC is a private real estate debt fund that pays verified accredited investors a fixed 8% to 10.5% annual rate, monthly, from performing senior lien loans and notes, with no management or performance fees. Principal is scheduled to be returned at maturity. The fund's objective is capital preservation first, with fixed monthly income.
Where does my claim sit in the capital structure? +
At the top. Your Secured Term Certificate is a legally binding obligation of the fund, and a UCC-1 filing records your secured interest in the fund's assets. The portfolio itself holds performing senior lien loans and notes where borrower equity absorbs losses before the fund's position is touched. Your claim is contractual, not residual.
Why debt instead of equity real estate? +
Equity is a residual claim: it collects last, absorbs losses first, and its distributions are discretionary. A performing loan pays a stated amount on a stated schedule because the borrower is legally obligated to pay it. The fund holds the lender's seat, where income is contractual and someone else's equity takes the first loss.
What loan-to-value do you target, and why? +
We target conservative loan-to-value ratios so that meaningful borrower equity stands between a market decline and your capital. The cushion is purchased at closing, not hoped for later.
How are valuations and loan files verified? +
Independently, before capital moves. Every property value is established through independent appraisal or broker price opinion rather than seller representations; a valuation we did not independently verify is a valuation we do not have. Loan files are reviewed page by page, and lien position and chain of assignments are confirmed, because paperwork failures are principal failures.
What happens when a borrower defaults? +
At conservative LTV, a default is an operational event, not automatically a loss event. The fund holds a recorded legal claim and has six resolution paths: loan modification, forbearance, deed in lieu, short payoff, selling the note, or foreclosure and recovery, with lending weighted toward states where recovery is fast and predictable. Approximately 8% of capital raised is held in reserve to carry costs through a workout.
Does “fixed” mean guaranteed? +
No, and an operator who lets you believe otherwise has told you something important about themselves. Fixed means contractual: a stated rate on a stated schedule, enforced by a recorded claim on real property. The risks are operational: borrower default, valuation error, state recovery timelines, and the fund being newly formed. Each is managed at underwriting, and the full risk factors are in the Private Placement Memorandum. This is a private investment, not a bank deposit, and it is not FDIC insured.
What are the fees, and how are you paid? +
There are no fees to you: no management fee, no performance fee, no carried interest, and no acquisition fees. The Fund Manager is paid last, earning only the spread that remains after investors receive their full certificate rate and fund expenses are met. The rate on your certificate is the rate that reaches you.
Is your own capital in these positions? +
Yes. Principal capital is invested in the same asset class and positions investors are asked to fund.
How does this fit retirement and tax planning? +
Self-directed IRAs and Roth SDIRAs are accepted with a qualified custodian. Distributions are ordinary interest income reported on a 1099-INT: no K-1s, no depreciation pass-through, and interest income is generally not subject to UBIT inside an IRA. Consult your tax advisor.
What is the liquidity profile? +
Private debt trades by negotiation, not on an exchange, and certificates are term instruments: 24, 36, or 60 months, with interest paid monthly and principal scheduled to be returned at maturity. Early redemption is possible but not guaranteed, subject to available funds and Manager approval, and a 1.25% fee may apply. Capital that may be needed next quarter does not belong in an instrument built for years.
Who can invest, and what is the process? +
Verified accredited investors, under SEC Rule 506(c); entities may also qualify. Verification is completed during onboarding through Accredd, a third-party verification service, or by a CPA letter, as federal rules require. Request the offering documents below, review the Private Placement Memorandum with your advisors, and interest begins accruing the day your investment is funded, with the first monthly payment within 30 days.
Request Access
See if the fund fits your portfolio
Essential Income Fund · Fixed 8% to 10.5% · Paid Monthly · +1% rate at $100K+
Apply to Invest